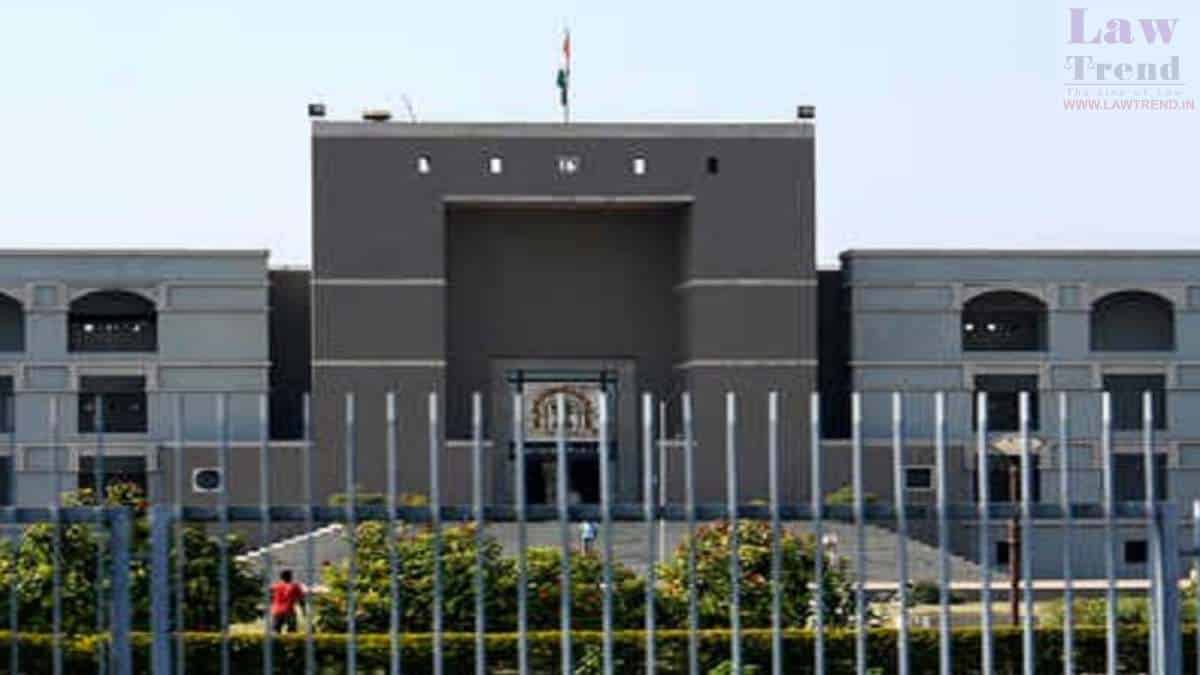
The Gujarat High Court, in a significant ruling, quashed a notice issued under Section 148 of the Income Tax Act, 1961, against Hareshkumar Bhupatbhai Panchani, holding that reopening an income tax assessment based on a mere change of opinion is not permissible in law. The judgment, delivered by a division bench comprising Justice Bhargav D.
No Reassessment Under Section 148 for Mere “Change of Opinion” by Assessing Officer: Gujarat High Court